
Primary Market Watch: Treasury Bills Post Auction Analysis – 14 October 2026

Post-MPR bullish momentum paused as 364-day rate edges up 5bps
The Central Bank of Nigeria (CBN), on behalf of the Federal Government, conducted the Treasury bills auction on Wednesday, 14 October 2026, offering N450 billion across the three standard maturities, half of the N900 billion offered at the previous auction on 7 October. The 364-day offer was reduced to N350 billion from N700 billion, while the 91-day and 182-day offers were cut to N50 billion each from N100 billion.
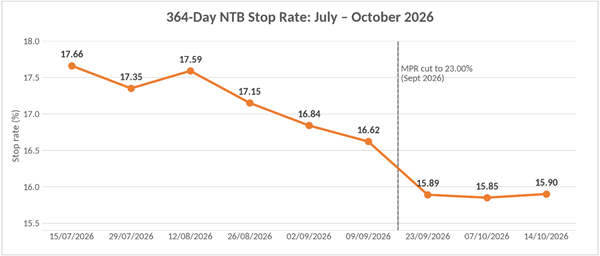
The auction attracted total subscriptions of N1.03 trillion, 42% lower than the N1.77 trillion recorded at the previous auction, although the smaller offer size lifted the overall bid-to-cover ratio to 2.29x from 1.97x. However, the DMO allotted only N269.06 billion, about 40% below the offer size, as it rejected a large share of bids on the 364-day bill. Stop rates on the 91-day and 182-day bills were maintained at 15.50% and 15.80%, respectively, while the 364-day stop rate edged up by 5 basis points to 15.90%, its first increase since August, signalling a pause in the post-MPR downward momentum in primary market rates.
Market Backdrop
Ahead of the Treasury bills auction, system liquidity rose to N6.30 trillion from N3.71 trillion at the close of the previous week, supported largely by OMO maturities of N2.41 trillion. However, benchmark Treasury bill yields reversed part of their recent decline, with the average secondary market yield rising by 22 basis points to 17.86% on 13 October from 17.64% on 7 October. The increase was driven mainly by the ends of the curve, as the 1-month and 12-month benchmark yields rose by 94 and 61 basis points to 17.75% and 18.38%, respectively, while the 9-month yield rose by 15 basis points to 18.23%. In contrast, the 3-month and 6-month benchmark yields declined by 49 and 11 basis points to 16.88% and 18.04%, respectively.
The uptick in secondary market yields, despite stronger system liquidity, suggests that investors are seeking higher returns following the sharp repricing that trailed the MPR cut.
| Tbill Yield | 07/10/2026 | 13/10/2026 | % Change |
| 1M | 16.81 | 17.75 | 0.94 |
| 3M | 17.37 | 16.88 | -0.49 |
| 6M | 18.15 | 18.04 | -0.11 |
| 9M | 18.08 | 18.23 | 0.15 |
| 12M | 17.77 | 18.38 | 0.61 |
| Avg. Yield | 17.64 | 17.86 | 0.22 |
Source: CBN, FMDA
Auction Outcome
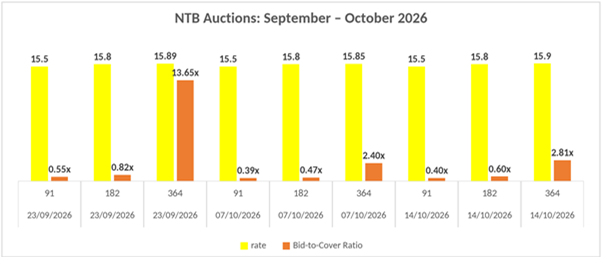
Investor demand remained concentrated on the 364-day Treasury bill, which attracted subscriptions of N982.21 billion against an offer of N350 billion, translating to a bid-to-cover ratio of 2.81x, up from 2.40x at the previous auction. However, the DMO allotted only N220.00 billion for the tenor, about 37% below the amount offered and roughly 22% of total bids, with bids ranging as high as 18.18%.
Demand at the shorter end of the curve remained weak. The 91-day Treasury bill attracted subscriptions of N19.91 billion against N50 billion offered, resulting in a bid-to-cover ratio of 0.40x, while the 182-day bill recorded subscriptions of N30.10 billion against N50 billion offered, translating to a bid-to-cover ratio of 0.60x. The DMO allotted N19.52 billion and N29.54 billion on the 91-day and 182-day bills, respectively, filling almost all bids at both tenors.
Stop rates were maintained at 15.50% and 15.80% for the 91-day and 182-day tenors, respectively, while the 364-day stop rate rose by 5 basis points to 15.90%, suggesting that the DMO is resisting upward pressure on rates by rejecting higher bids rather than raising its borrowing cost.
Source: CBN, FMDA
CBN, FMDA
Market Insight
- Demand for Treasury bills weakened further, with total subscriptions falling to N1.03 trillion from N1.77 trillion, despite a significant improvement in system liquidity to N6.30 trillion.
- The DMO demonstrated strong price discipline, allotting only N269.06 billion against an offer of N450 billion and rejecting about 78% of bids on the 364-day bill, rather than accepting higher rates.
- The 5 basis points uptick in the 364-day stop rate to 15.90%, the first increase since August, suggests that the post-MPR bullish momentum in the primary market has paused.
- The uptick in the 364-day stop rate mirrors the upward adjustment in the secondary market, where the 12-month benchmark yield rose by 61 basis points to 18.38%, indicating that investors are pricing in higher yields at the long end of the curve.
- Following the N968.47 billion raised at the previous auction, the lower offer and allotment this week suggest that the government is moderating its borrowing pace to avoid pushing rates higher.