
FMDA Weekly Market Report November 16, 2026

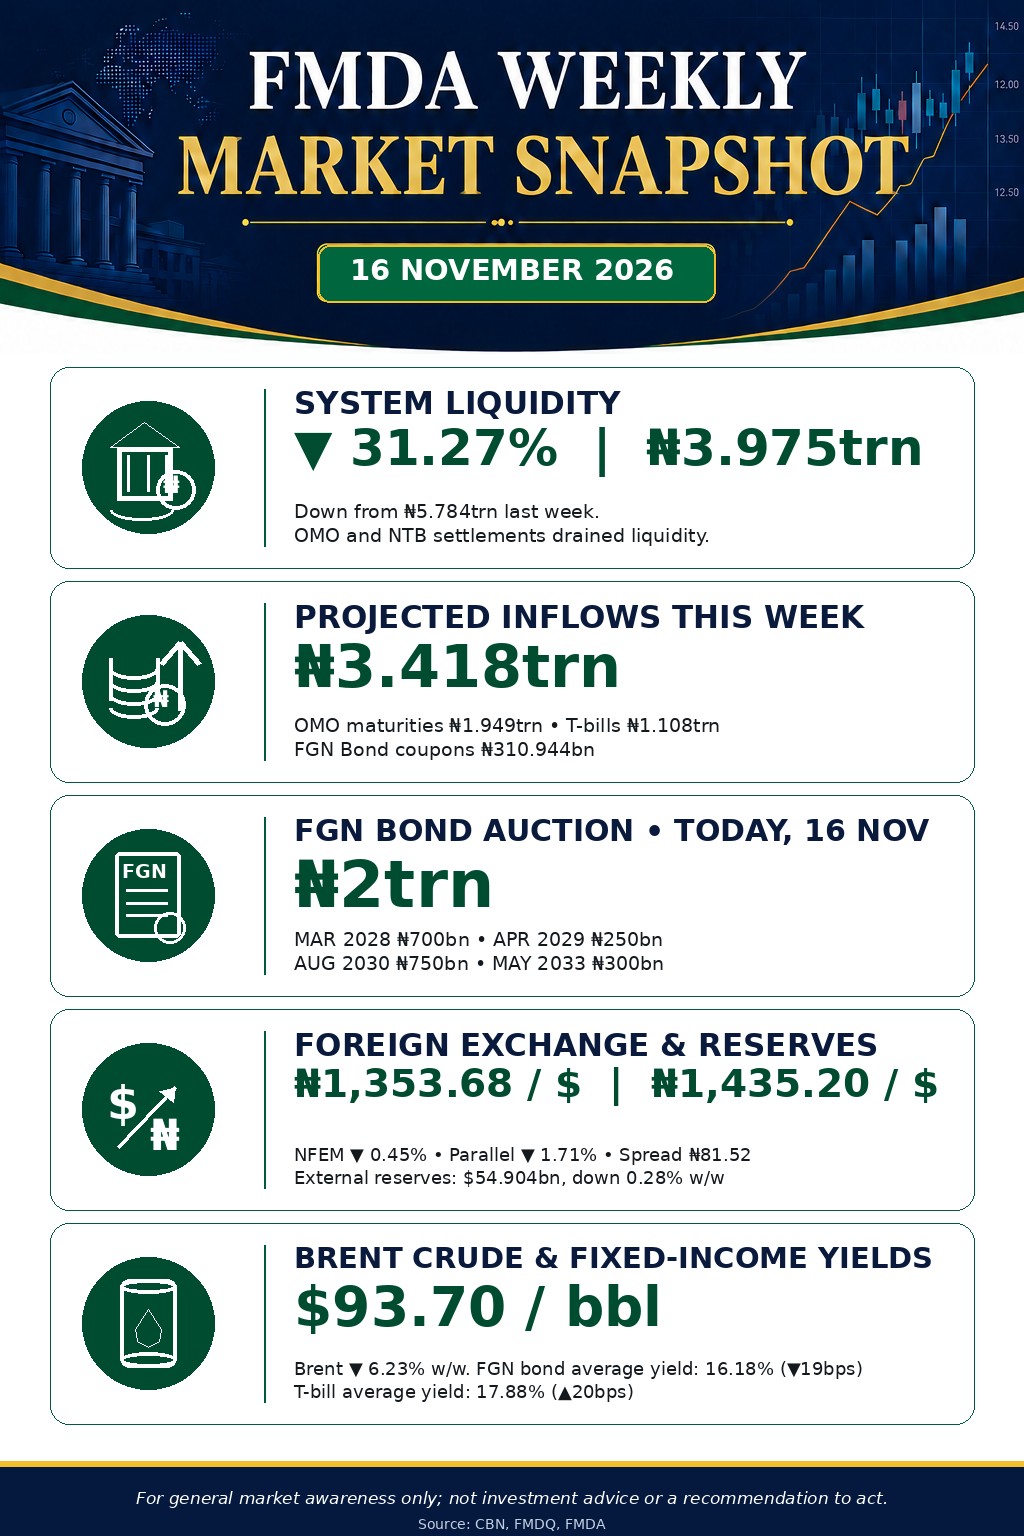
- System liquidity fell 31.27% w/w to N3.975trn from N5.784trn, as CBN’s OMO auction on 10 November absorbed N3,853.75bn and the DMO’s NTB auction settlement on 12 November drained a further N713.304bn, together outweighing N2.298trn of OMO maturities and other inflows during the week.
- Inflows are projected at N3.418trn this week, led by N1.949trn of OMO maturities, N1.108trn of T-bill maturities and N310.944bn of FGN Bond coupon payments; the DMO returns to the primary market today (16 November) with a N2trn FGN Bond auction (N700bn MAR 2028, N250bn APR 2029, N750bn AUG 2030, N300bn MAY 2033), leaving
- that auction as the week’s main scheduled drain.
- The naira on the average weakened further this week, the NFEM rate eased 0.45% to N1,353.68/$ while the parallel rate fell 1.71% to N1,435.20/$, widening the premium between the two windows to N81.52 from N62.96 the week before, extending last week’s reversal of October’s narrowing trend.
- External reserves slipped below the $55bn mark, down 0.28% w/w to $54.904bn from $55.133bn, a second straight weekly decline, as CBN continue to meet market obligation.
- Average Brent crude extended its slide, down 6.23% w/w to $93.70/bbl from $99.97, touching an 11-week low as the IEA forecast the oil market returning to surplus on recovering Gulf exports, while easing US-Iran tensions continued to deflate the geopolitical risk premium.
- FGN bond yields eased 19bps on average to 16.18%, led by the 7-year (-100bps), while Treasury bill yields rose 20bps to 17.88%, led by the 6-month (+74bps), a reversal of last week’s divergence.
Kindly download the full report here