
Primary Market Watch: Treasury Bills & OMO Post Auction Analysis – 7 October 2026

Market continues to adjust to MPR reset as primary market rates hold steady
The Central Bank of Nigeria (CBN) conducted Open Market Operations (OMO) and Treasury bills auctions during the week, as the market continued to adjust to the Monetary Policy Committee’s (MPC) decision to cut the Monetary Policy Rate (MPR) by 350 basis points to 23.00% in September.
At the OMO auction conducted on 6 October 2026, the CBN offered N2.00 trillion across the 147-day and 182-day tenors, lower than the N2.50 trillion offered at the previous auction on 29 September, when a 266-day bill was also offered. The auction attracted total subscriptions of N3.51 trillion, translating to a bid-to-cover ratio of 1.76x, compared with N6.40 trillion (2.56x) at the previous auction. Demand was concentrated on the 182-day bill, which recorded subscriptions of N2.69 trillion (2.69x), while the 147-day bill was undersubscribed at N817.95 billion (0.82x). The CBN allotted a total of N3.31 trillion, about 65% above the offer size, with almost all bids on the 182-day bill filled.
Stop rates were broadly unchanged, declining marginally by 2 basis points each to 17.22% (147-day) and 16.92% (182-day). Notably, the 147-day tenor cleared above the longer 182-day tenor for a second consecutive auction, while OMO rates remain well above comparable Treasury bill rates, underscoring the CBN’s continued use of OMO to manage system liquidity.
Following the OMO auction, the Central Bank of Nigeria (CBN), on behalf of the Federal Government, conducted the Treasury bills auction on Wednesday, 7 October 2026, offering N900 billion across the three standard maturities, up from N500 billion at the previous auction on 23 September, with the 364-day offer raised to N700 billion from N300 billion. The auction attracted subscriptions of N1.77 trillion, 58% lower than the N4.23 trillion recorded at the previous auction, translating to an overall bid-to-cover ratio of 1.97x compared with 8.46x previously. Despite the weaker demand, the DMO allotted N968.47 billion, about 8% above the offer size and nearly double the N497.59 billion raised at the previous auction. Stop rates were largely unchanged, with the 91-day and 182-day rates held at 15.50% and 15.80%, respectively, while the 364-day stop rate eased by 4 basis points to 15.85%.
Market Backdrop
Ahead of the Treasury bills auction, system liquidity moderated to N3.96 trillion from N4.86 trillion at the close of the previous week, as the CBN’s OMO sales more than offset inflows from OMO maturities. Meanwhile, benchmark Treasury bill yields declined further across the curve, with the average secondary market yield falling by 98 basis points to 17.48% on 6 October from 18.46% on 23 September. The 3-month benchmark yield recorded the largest decline, falling by 158 basis points to 16.43%, while the 1-month, 6-month, 9-month and 12-month benchmark yields declined by 85, 74, 83 and 90 basis points to 16.40%, 17.94%, 18.23% and 18.40%, respectively.
The continued decline in secondary market yields reflects the market’s ongoing adjustment to the MPR reset. However, tighter system liquidity, coupled with attractive OMO rates, moderated demand for Treasury bills at the auction.
| Tbill Yield | 23/09/2026 | 06/10/2026 | % Change |
| 1M | 17.25 | 16.40 | -0.85 |
| 3M | 18.01 | 16.43 | -1.58 |
| 6M | 18.68 | 17.94 | -0.74 |
| 9M | 19.06 | 18.23 | -0.83 |
| 12M | 19.30 | 18.40 | -0.90 |
| Avg. Yield | 18.46 | 17.48 | -0.98 |
Source: CBN, FMDA
Auction Outcome
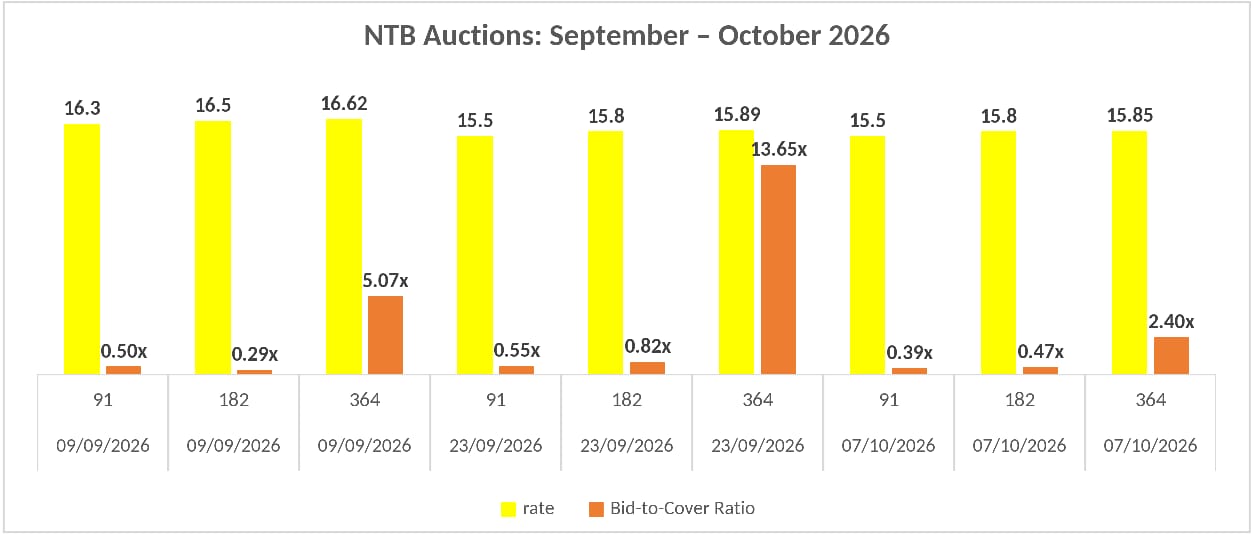
Investor demand remained concentrated on the 364-day Treasury bill, which attracted subscriptions of N1.68 trillion against an increased offer of N700 billion, translating to a bid-to-cover ratio of 2.40x, down from 13.65x at the previous auction. Nonetheless, the DMO allotted N885.00 billion for the tenor, about 26% above the amount offered, accounting for over 91% of total allotment.
Demand at the shorter end of the curve remained weak. The 91-day Treasury bill attracted subscriptions of N39.42 billion against N100 billion offered, resulting in a bid-to-cover ratio of 0.39x, while the 182-day bill recorded subscriptions of N46.87 billion against N100 billion offered, translating to a bid-to-cover ratio of 0.47x. The DMO allotted N38.55 billion and N44.92 billion on the 91-day and 182-day bills, respectively, filling almost all bids at both tenors.
Stop rates were maintained at 15.50% and 15.80% for the 91-day and 182-day tenors, respectively, while the 364-day stop rate declined by 4 basis points to 15.85%, suggesting that the DMO is holding its pricing stance following the sharp repricing at the previous auction.
Source: CBN, FMDA
Market Insight
- Demand for Treasury bills moderated significantly, with total subscriptions falling to N1.77 trillion from N4.23 trillion, as tighter system liquidity and a larger offer size weighed on the bid-to-cover ratio.
- OMO bills continue to offer a premium over Treasury bills, with the 182-day OMO stop rate of 16.92% about 112 basis points above the 182-day NTB stop rate of 15.80%, drawing liquidity away from the Treasury bills market.
- The DMO raised N968.47 billion, nearly double the amount raised at the previous auction, while keeping stop rates broadly unchanged, in line with our expectation that the government would come to the domestic debt market to raise funds at a lower cost following the MPR cut.
- With secondary market yields declining by 98 basis points while stop rates held steady, the 364-day stop rate of 15.85%, equivalent to a true yield of 18.83%, now sits about 43 basis points above the 12-month benchmark yield of 18.40%, reversing the gap observed at the previous auction.
- The 364-day stop rate has now declined by 181 basis points since mid-July, from 17.66% on 15 July to 15.85%, reflecting a sustained reduction in the government’s short-term borrowing cost.
- Looking ahead, the trajectory of yields will depend on system liquidity conditions, the pace of CBN’s OMO issuances and signals from the next MPC meeting.