Primary Market Watch: Treasury Bills Post Auction Analysis – 23 September 2026

Higher demand, MPR cut, pushes treasury bill rate downward in the primary market
The Central Bank of Nigeria (CBN), on behalf of the Federal Government, conducted the Treasury bills auction on Wednesday, 23 September 2026, against the backdrop of the Monetary Policy Committee’s (MPC) decision to cut the Monetary Policy Rate (MPR) by 350 basis points to 23.00% from 26.50%, alongside a significant improvement in system liquidity.
The DMO offered N500 billion across the three standard maturities, lower than the N750 billion offered at the previous auction on 9 September, with the 364-day offer reduced to N300 billion from N500 billion. The auction attracted strong investor demand, with total subscriptions rising to N4.23 trillion from N2.64 trillion at the previous auction, translating to an overall bid-to-cover ratio of 8.46x compared with 3.52x previously.
Despite the heavy demand, the DMO allotted N497.59 billion, marginally below the offer size, as undersubscription and bid rejections at the short end offset over-allotment on the 364-day bill. Notably, stop rates declined across all tenors by between 70 and 80 basis points, with the 364-day stop rate falling by 73 basis points to 15.89%, further reducing the government’s borrowing cost. This is in line with our expectation that, following the MPR cut, the government would now come to the domestic debt market to raise funds at a lower cost.
Market Backdrop
Ahead of the Treasury bills auction, system liquidity improved significantly, rising to N7.45 trillion from N2.86 trillion at the close of the previous week. Benchmark Treasury bill yields also moderated, with the average secondary market yield declining by 36 basis points to 18.46% on 22 September from 18.82% on 9 September. The decline was driven mainly by the short and medium segments of the curve, as the 1-month, 3-month and 6-month benchmark yields fell by 38, 89 and 44 basis points to 17.16%, 17.00% and 18.98%, respectively. In contrast, yields at the longer end remained broadly stable, with the 9-month and 12-month benchmark yields at 19.90% and 19.27%, respectively.
The combination of ample system liquidity and the MPR cut, which reinforces expectations of a lower interest rate environment, supported strong demand for government securities, particularly the one-year Treasury bill, as investors moved to lock in yields.
| Tbill Yield | 09/09/2026 | 22/09/2026 | % Change |
| 1M | 17.54 | 17.16 | -0.38 |
| 3M | 17.89 | 17.00 | -0.89 |
| 6M | 19.42 | 18.98 | -0.44 |
| 9M | 20.00 | 19.90 | -0.10 |
| 12M | 19.26 | 19.27 | 0.01 |
| Avg. Yield | 18.82 | 18.46 | -0.36 |
Source: CBN, FMDA
Auction Outcome
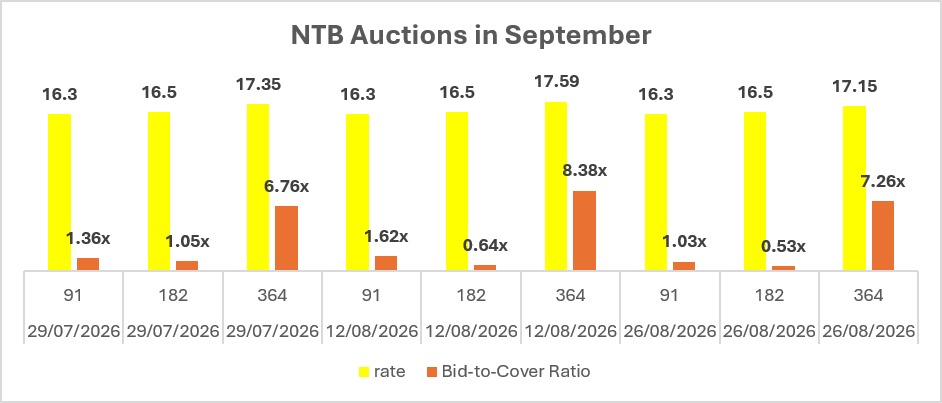
Investor demand remained heavily concentrated on the 364-day Treasury bill, which attracted subscriptions of N4.09 trillion against a reduced offer of N300 billion, translating to a bid-to-cover ratio of 13.65x, up from 5.07x at the previous auction. This reflects investors’ strong appetite to lock in longer-dated yields following the MPR cut. In response, the DMO allotted N447.07 billion for the tenor, about 49% above the amount offered.
Demand at the shorter end of the curve remained weak. The 91-day Treasury bill attracted subscriptions of N54.93 billion against N100 billion offered, resulting in a bid-to-cover ratio of 0.55x, while the DMO allotted only N11.03 billion. Similarly, the 182-day bill recorded subscriptions of N82.23 billion against N100 billion offered, translating to a bid-to-cover ratio of 0.82x (up from 0.29x at the previous auction), with N39.49 billion allotted.
Stop rates declined across all tenors, falling by 80 basis points to 15.50% for the 91-day, by 70 basis points to 15.80% for the 182-day, and by 73 basis points to 15.89% for the 364-day tenor, reflecting the combined impact of the MPR cut, stronger liquidity and robust investor demand.
Source: CBN, FMDA
Market Insight
- Total subscriptions rose to N4.23 trillion from N2.64 trillion at the previous auction, with the overall bid-to-cover ratio improving to 8.46x from 3.52x, underscoring strong appetite for Treasury bills amid improved liquidity.
- The 350 basis points MPR cut to 23.00% was quickly reflected in primary market pricing, with stop rates declining by 70 to 80 basis points across all tenors.
- The 364-day stop rate has now fallen by 177 basis points since mid-July, from 17.66% on 15 July to 15.89%, highlighting a sustained decline in the government’s short-term borrowing cost.
- Demand remained heavily concentrated at the long end, while undersubscription at the 91-day and 182-day tenors suggests continued investor preference for duration as investors position for lower rates.
- Primary market stop rates remain well below secondary market yields, with the 364-day stop rate at 15.89% compared with a 12-month benchmark yield of 19.27%, suggesting room for further downward repricing in the secondary market.
- Looking ahead, the trajectory of yields will depend on system liquidity conditions, the transmission of the MPR cut and the pace of CBN’s liquidity management operations.
